Publikation
Datum:
September delivered three central bank rate hike decisions (ECB on 10 Sept, Fed on 16 Sept, BOJ on 18 Sept), but more significantly a global bond rout that pushed long-dated yields to multi-decade highs and left the Treasury's tripled buybacks (see page 4) unable to cap them, with France as the European flashpoint (see further).
EUROZONE
Deposit Rate: 2.50%
+25bp on 10 Sept;
29 Oct hike ~30–40%
HICP: 3.8% y/y (Sept flash)
up from 3.2%; core 2.5%; energy +18.8%
ECB hiked as expected, and the projections did the talking.
On 10 September the Governing Council raised all three key rates by 25bp, unanimously, taking the deposit rate to 2.50%, its second hike this year; Lagarde called it “a no brainer.” Staff projections kept 2026 inflation at 3.0% but lifted 2027 to 2.5% and 2028 to 2.1%.
Inflation then re-accelerated.
The September flash HICP jumped to 3.8%, the highest since September 2023, with energy up 18.8% y/y, core at 2.5% and Germany at 3.3%.
The pace is the debate.
Lagarde said on 28 September that a measured response remains appropriate as no dangerous second-round effects have appeared yet; markets price a 29 October hike at roughly 30–40% and a December hike above 70%.
United States
Fed Funds: 3.75 – 4.00%
+25bp, 12–0 (16 Sept); Oct hike ~20%
US CPI: 3.4% y/y (Aug)
steady vs July; core 2.4%, 5-year low
Fed hiked unanimously and signaled upcoming rate hikes.
On 16 September the FOMC raised the target range by 25bp to 3.75–4.00% in a 12–0 vote, its first hike since 2023, after three members had dissented in favour of a hike in July. Sixteen of 18 participants (Chair Warsh submits no dot) expect at least one more hike this year, four expect two, and the median year-end range is 4.00–4.25%. Warsh said inflation “is too high and has been for too long” and that the predominant focus is the price stability side of the dual mandate.
Does employment still matter?
August payrolls beat at +162k (consensus ~53k, unemployment 4.1%), but September payrolls on 2 October fell to +29k, unemployment rose to 4.2% and earlier months were revised down by 60k. With softer than expected August PCE (3.4% y/y) and “no urgency” remarks from the New York Fed's Williams and Vice Chair Jefferson, October hike odds fell from ~70% to ~20% in one week while December stays above 75%: jobs data shape the timing, inflation sets the direction.
August CPI: 3.4%, core 2.4%.
Headline was steady (+0.4% m/m) as gasoline rose 27% y/y, while core eased to a five-year low.
Bonds & Commodities:
The Treasury tripled its buyback size to up to $6bn per operation on 9 September. Despite that, the US 10-year yield rose from 4.76% to 5.29% (highest since 2007) and the 30-year to 5.64% (highest since 2002), Japan's 10-year passed 3% for the first time since 1996 and Germany's 10-year hit its highest since 2011. Brent rose about 14% to around $100 after fighting resumed on 30 August, and gold fell about 7% as yields reached their highest since 2008.
Equities near records, volatility low:
the Nasdaq Composite set a record close on 22 September and ended the month about 1.4% below it, the S&P 500 (last record on 13 August) finished about 2% below its peak, and the Nasdaq 100 added another record on 2 October. The VIX closed September at 16.3, below its long-run average of around 20 and not far from its 2026 low of 14.2, so investor confidence in equities and in the AI investment cycle looks unshaken. Yet ESMA warned on 10 September that stretched valuations risk an abrupt correction, breadth is weak (Dow -4.3%, DAX -4.0%, equal-weight S&P lagging by 4.6 points) and Treasury volatility (MOVE) sits near 110.
Crypto:
Crypto showed resilience despite the Senate's 49-50 failure to advance the Clarity Act on 15 September, which sent Bitcoin down about 4% to around $75,000 and cut the odds of enactment this year to single digits spot ETF inflows of about $2.65bn lifted it to an eight-month high near $87,000 and a September close of roughly $83,600 (+6.4%, still about a third below its October 2025 peak). With legislation unlikely before a new Congress, prospects now rest on SEC and CFTC rulemaking rather than a government-driven act.
How France's borrowing premium over Germany went from near-parity to the widest since the 2012 eurozone crisis.
OAT-Bund spread: ~140bp
widest since 2012;
130bp+ on 1 Oct
10Y OAT yield: ~4.9%
highest since 2002;
neared 5% on 1 Oct
France now wider than Italy
OAT-Bund ~133bp
vs BTP-Bund ~109bp (1 Oct)
2027 deficit target: 5%
from 5.4% in 2026;
debt above 120% of GDP
Two prime ministers were ousted over budget plans (Barnier in December 2024, Bayrou in September 2025), and Lecornu secured the 2026 budget only in February, after two failed no-confidence votes, by suspending the 2023 pension reform. On 1 October his minority government presented the 2027 budget: about €54bn of savings and tax measures, €43bn of them new, to cut the deficit from 5.4% to 5% of GDP. It assumes 1% growth, which the fiscal watchdog calls optimistic, and without the cuts the deficit would approach 6.5%. Presidential elections in April 2027 add further uncertainty.
Since the June 2024 snap election, France's premium over Germany has consequently risen, from roughly 20–50bp, essentially on par with Germany's “core” peers, to about 140bp in early October 2026, the widest premium spread since the 2012 eurozone debt crisis. The spread broke above 100bp in September for the first time since 2012, rising from about 85bp at the start of the month to over 110bp by 29 September. Over the same period the rest of the euro area moved the other way, with the average spread falling from ~70bp to ~40bp by June. By 1 October France's 10-year yield, near 4.9% and the highest since 2002, sat above Italy's (~4.7%).
France is rated Aa3 (negative outlook) at Moody's and A+ at Fitch and S&P, well above Italy (Baa2 at Moody's), yet France is now paying more to borrow than Italy does. That rating crossover suggests markets price political and execution risk faster than agencies can reflect it in their ratings. Market commentators named France, the UK and Japan as the most vulnerable to the global bond selloff and noted that Italy now trades inside France. In 2012 the ECB's OMT calmed the eurozone crisis without ever being used. The TPI tool, introduced in 2022, has never been tested at France's scale and requires compliance with the EU fiscal framework, a harder call when the budget itself is the problem.
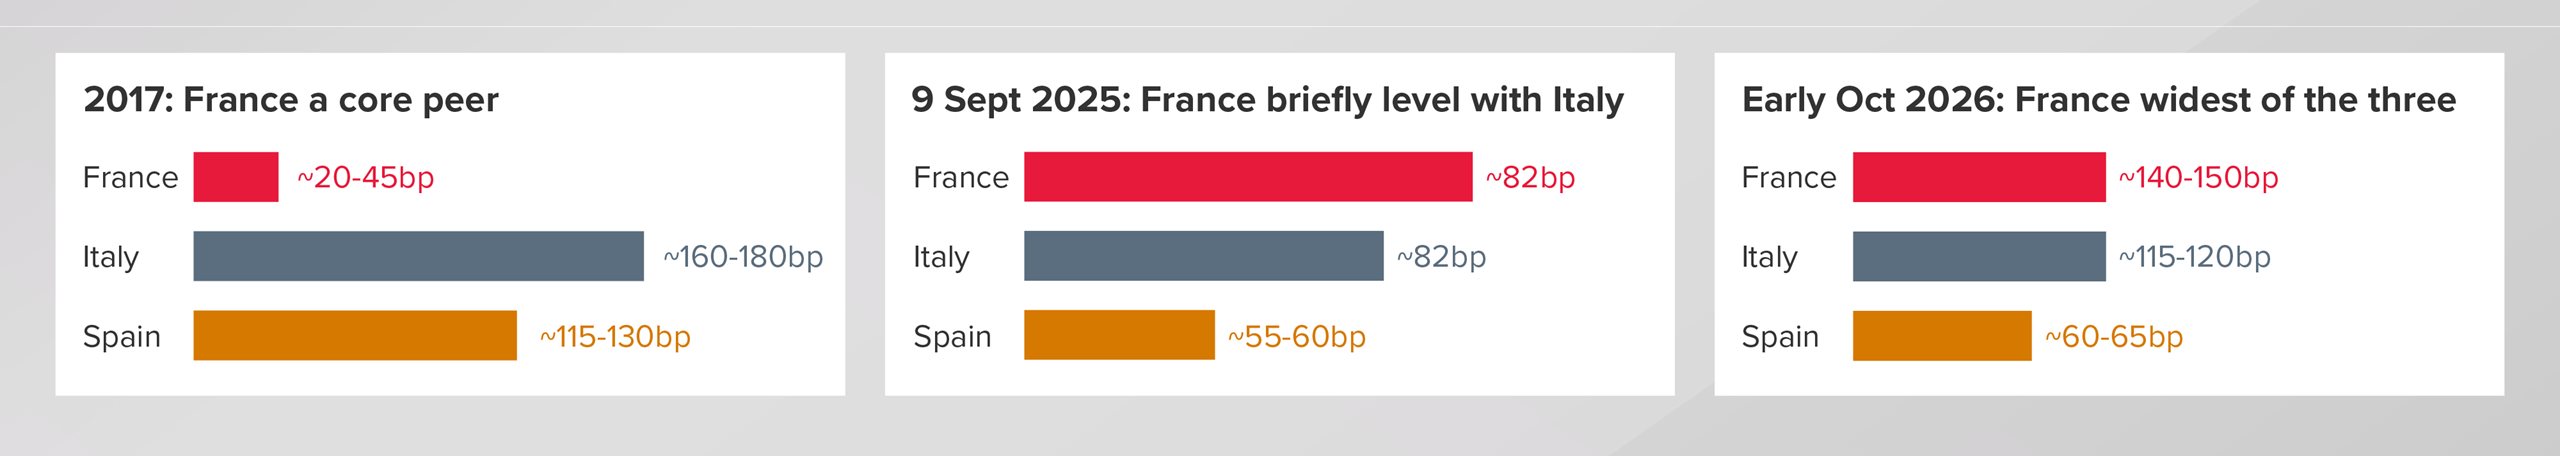
10-year government bond spreads over Bunds (bp). Bars show range midpoints and are approximate.
Click to view the picture in full size
The fact that spreads for southern Eurozone economies, historically more vulnerable to market shocks and investors’ lack of trust, are trading below the OAT-Bund spread indicates that this is a France-specific premium layered on a global long-term rates trend, not yet a market shock or a systemic eurozone crisis. Spillover effects are modest so far: Italy's 10-year spread rose from 102bp to 109bp on 1 October, its biggest daily jump since 2020, during a broad global bond selloff. For banks and portfolio managers, French government bonds sit in liquidity buffers and collateral pools across the euro area, so repricing hits HQLA valuations and haircuts well beyond French banks’ balance sheets.
What to watch:
the Finance Bill reaches the National Assembly by 6 October, with the EU's mid-October budget deadline close behind; Moody's reviews France on 23 October (Aa3, negative outlook) and S&P on 27 November (A+, stable); and whether the recent widening in Italy’s spread persists beyond one day.
Global yields at multi-decade highs, three central banks are tightening monetary policy, and a bond market that largely ignored the Treasury's interventions: what September means for treasury and risk teams. The implications, key takeaways, and market figures that frame them.
September's selloff looks less driven by short-term inflation prints or central bank messaging than by a structural imbalance between bond supply and reliable demand. The Treasury tripled its buyback size of its long-term bonds to $6bn on 9 September and yields rose anyway, and the Fed, ECB and BOJ all hiked without turning the long end. Market observers argue that the pressure comes from an imbalance: issuance by governments, hyperscalers and companies far exceeds the pool of reliable buyers, with China, Japan, the Gulf and now Norway's wealth fund (proposing about $80bn of Treasury cuts) less dependable. Other commentators highlight a peacetime deficit near 6% of GDP, sticky inflation and AI-related capital demand, and point to an unwinding yen carry trade that used to fund deficits cheaply. Real yields confirm it: the 10-year TIPS yield rose about 44bp in September, its fastest monthly rise in four years. For banks this could mean mark-to-market pressure on securities books and HQLA portfolios, higher IRRBB sensitivity at the long end, higher funding costs, and collateral haircuts that move with volatility.
At his 16 September press conference Kevin Warsh said the predominant focus is price stability, and the hike followed a strong August payrolls report (+162k against ~53k expected). Yet the labour market has not left the reaction function: the weak September report (+29k, unemployment 4.2%), softer August PCE (3.4% y/y) and calls from Fed officials Williams and Jefferson for more data cut October hike odds from about 70% to about 20% within a week, while a December hike remains priced above 75%. For the world’s biggest economy, the risk is two-sided. A cooling labour market alongside inflation well above target (with high energy prices, Brent near $100, US gasoline +27% y/y) points to potential for stagflation-style credit stress in consumer and energy-sensitive segments, while the monetary policy path for major economies could now shift with each data release because central bankers decline to provide forward guidance.
| Date | What to watch |
| 14 Oct: | US September CPI; third-quarter bank earnings season starts mid-October (net interest income and trading against bond-book losses). |
| 23 Oct and 27 Nov: | Moody's (Aa3, negative outlook) and S&P (A+) review France. |
| 27–28 Oct: | FOMC (October hike ~20%, December above 75%). |
| 29–30 Oct: | ECB (hike ~30–40%, December favoured) and BOJ with its outlook report, next hike seen around December. |
| 3 Nov: | US midterm elections; the enlarged Treasury buyback window ends on 4 November, with the quarterly refunding announcement in early November. |
| 6 Nov and 8–9 Dec: | US October jobs report; FOMC with new projections. |
| 11 Dec: | the US stopgap funding expires, so a shutdown is possible again (161 days of partial shutdowns in FY2026); 17 Dec: ECB. |
| Throughout: | Strait of Hormuz, oil near $100 and the 10-year Treasury against 5.3%. |
| Metric | Value |
| US CPI (y/y, June) | 3.4% |
| Eurozone HICP (y/y, August, flash) | 3.8% |
| Fed Funds target range | 3.75% – 4.00% |
| ECB Deposit Facility Rate | 2.50% |
| US 10Y Treasury yield | 5.29% |
| US 30Y Treasury yield | 5.64% |
| German 10Y Bund yield | 3.6% |
| EUR/USD | 1.1355 |
| Gold (USD/oz) | $4,170 |
| Brent crude (USD/bbl) | $103 |